July 8, 2022
4 mins read

Forex Crisis Puts Pakistan on Lanka Mode

Civil unrest in brewing in Pakistan as fragile forex position leading to fuel import crisis and paucity of goods … writes Dr Sakariya Kareem

Pakistan’s central bank, the State Bank of Pakistan (SBP) has warned its government about dwindling forex reserves and its impact on country’s ability to sustain imports. The decline in SBP’s Forex reserves, which fell to $8.24 billion on June 17 is likely to continue due to pressure of debt servicing and other payments in near future.

To preserve the diminishing Forex, SBP has advocated a temporary ban on import of all non-essential goods. It has apparently highlighted the risk ballooning fuel imports entail for the energy security of the country.
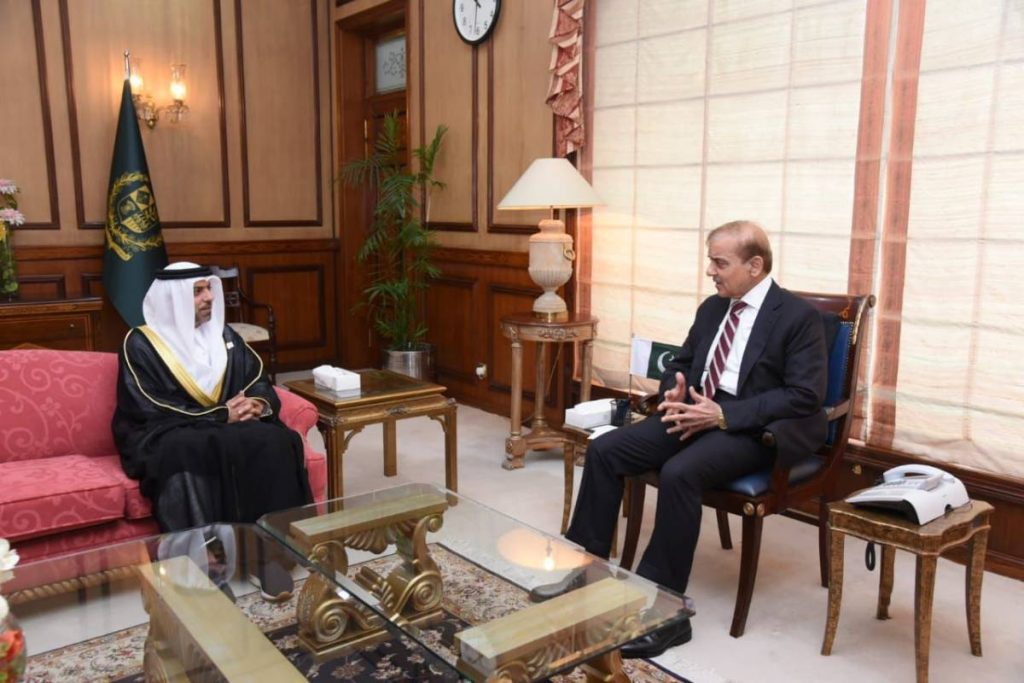
UAE to buy minority shares in Pak govt companies

Pakistan’s total petroleum imports stood $9.7 billion during fiscal year 2020-21. But as rising global prices pushed its import bill to more than $14.46 billion in July-April period of the current fiscal year and its Forex position tightened, the ramifications on Pakistan’s oil imports have been critical.

Warning that the rising energy imports are eating into Forex reserves, SBP fears that further erosion could seriously undermine Pakistan’s ability to import fuel. Targeting some decrease in fuel demand, the Pak government has already withdrawn many subsidies on fuel, which resulted in a sharp increase in domestic energy prices. However, it has not been able to bring down the import bill to a comfortable level. According to SBP, the Ministry of Energy & Petroleum should be asked to formulate and implement stringent policy measures to contain demand for energy products.

The rapidly depreciating local currency, i.e. Pakistani Rupee (PKR) is further compounding the problem. Its steady depreciation continues with exchange rate reaching from PKR199/USD on 6th June to PKR 207/US D on 6th July 2022. The situation has turned into a vicious cycle as depreciating currency leads to rise in fuel import bill which makes the fiscal position even weaker. On currency, SBP has recently attempted some large scale interventions in the market. However, its limited capacity to control the exchange rate has yielded only paltry returns.

Low level of Forex reserves has unnerving effect on international fuel suppliers also. Their decline in trust for Pakistan’s import capacity is revealed by a visible decline in acceptance of letters of credit (LC) issued by Pak banks. International banks as the receiving party in the LCs, are asking for a third-party bank for a confirmation; a guarantee that the Pak bank will pay the LC amount when it falls due. According to a banking professional quoted in Pakistani media, foreign banks are cautious dealing with local counterparts right now keeping in mind the position of the country’s foreign exchange reserves.
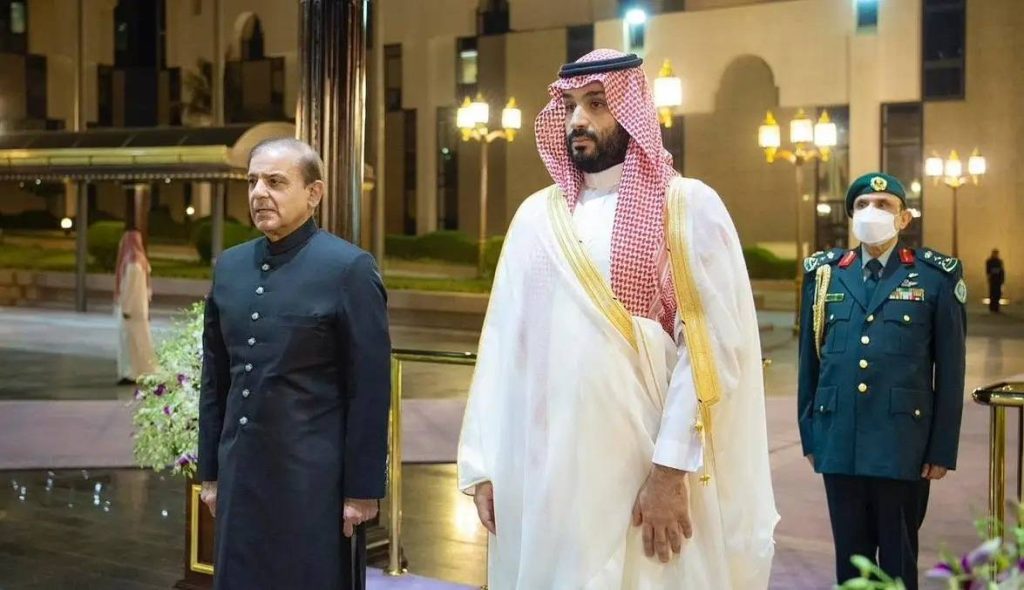
Pakistan renews ties with Riyadh

As a result, the recent tender auction by state-owned Pakistan State Oil (PSO) attracted pricier offers from suppliers which subsequently mean higher oil prices in the country. Moreover, most of PSO’s suppliers remained reluctant with only one supplier Idemitsu responding to its tender for supply of 54000 MTs of gasoline in July 2022. Bigger international players are either choosing to wait until the economic situation improves, or putting up bids at higher premiums to stay in the market.

Of late, Islamabad has relied heavily upon bilateral fuel import agreements on deferred payment basis with major gulf countries, i.e. Saudi Arabia and United Arab Emirates (UAE). Recently, the country was successful in securing resumption of a Saudi facility for providing oil on deferred payment. However, its monthly limit of $100 million is insufficient to provide a meaningful relief for the Forex reserves.

Meanwhile, Pak Finance Ministry is also predicting a gloomy picture for the economy and BoP position. It reportedly assessed that “the underlying macroeconomic imbalances associated with domestic and international risks are making growth outlook indistinct,” and that SBP’s demand management policy was unlikely to be successful in the face of supply side constraints and higher international commodity prices that may further erode the income levels.

Perceptions of a higher country risk have been further fuelled by the downgrades by global ratings agencies. Recently, Moody’s revised down Pakistan’s rating from stable to negative, rising credit default spreads for the country. So far, pressure from IMF has forced Islamabad to introduce some reforms in the energy market like fuel subsidy reduction and power tariff increase. However, in absence of any structural reforms, the country’s fiscal fate hangs majorly on two factors only: the generosity of its lenders and the movement of international crude prices.

Previous Story

Russia dismisses West’s ‘frenzied’ criticism

Next Story

Milling visits Gulf to deepen economic ties

Previous Story

Russia dismisses West’s ‘frenzied’ criticism

Next Story

Milling visits Gulf to deepen economic ties

Latest from Asia News

Pakistan Risks Overstretching Itself in Yemen War

Pakistan’s expanding military role in Saudi Arabia amid the Yemen conflict could strain its defence resources and fragile finances…reports Asian Lite News Desk Pakistan’s military involvement in the war in Yemen may prove unsustainable because of mounting financial pressures and competing security demands, according to a new report. Islamabad’s growing military presence in Saudi Arabia risks stretching its defence resources while exposing the country to greater strategic and economic challenges. An article by Andrew Wilson in One World Outlook describes Pakistan’s involvement as a case of “fiscal and strategic overreach”, arguing that the country lacks the financial flexibility to sustain an expanded military commitment. Pakistan’s external finances depend heavily on an International Monetary Fund (IMF) programme, financial support from Gulf countries and remittances from Pakistani workers in the region. The report argues that deeper military involvement in the conflict could place additional pressure on these sources of financial stability. It also warns that deploying troops and military equipment abroad could weaken Pakistan’s capacity to address security challenges along its eastern border and deal with two domestic insurgencies. The move could also draw Islamabad into a conflict it has sought to approach cautiously. A Reuters report in May, citing Pakistani security and government sources, said Islamabad had deployed around 8,000 troops, a squadron of approximately 16 aircraft, mostly JF-17 fighter jets, two drone squadrons and a Chinese HQ-9 air-defence battery to Saudi Arabia. According to those sources, Riyadh was financing the deployment, with Pakistani personnel operating the equipment. The sources also said a confidential agreement contemplated the possibility of deploying up to 80,000 troops. Islamabad has not confirmed those figures, although it has acknowledged its military presence in Saudi Arabia, including the deployment of fighter jets at King Abdulaziz Air Base from April. The One World Outlook article argues that Saudi financial support can cover allowances and operating expenses but cannot easily replace military equipment needed elsewhere or resolve the political and strategic challenges of participating in the Yemen conflict. Pakistan’s defence budget is another concern. For the 2026-27 financial year, the federal government allocated PKR 3 trillion, or approximately $10.8 billion, to defence services. The allocation represents an 18 per cent increase from the original PKR 2.55 trillion provision and amounts to around 2.1 per cent of projected gross domestic product (GDP). Defence spending accounts for approximately 16 per cent of the federal government’s PKR 18.8 trillion expenditure. Military pensions are budgeted separately at PKR 822 billion, while debt servicing costs stand at approximately PKR 8 trillion, more than two-and-a-half times the defence allocation. The report argues that these competing financial obligations leave little room for additional military expenditure without placing further pressure on public finances. Pakistan’s reliance on IMF assistance also limits its fiscal flexibility. The country must meet the conditions attached to the programme, including a primary budget surplus target of 2 per cent of GDP and continued restraint on development spending. According to the article, these requirements make it difficult for Islamabad to finance an additional military commitment without compromising other budgetary priorities. Pakistan’s economic indicators offer limited reassurance. Economic growth for the 2025-26 financial year is estimated at between 3.6 and 3.7 per cent, while inflation reached approximately 10.3 per cent in September following an energy price shock. Foreign exchange reserves stood at around $21.5 billion at the end of September. Although this marks an improvement from the low levels recorded in 2023, the report notes that the reserves cover only a few months of imports. Financial assistance from Gulf partners remains central to Pakistan’s external stability. The article says Islamabad holds approximately $8 billion in Saudi deposits at its central bank. In July, the State Bank of Pakistan said Riyadh had extended the maturity of $5 billion in deposits to December 2028, easing the country’s immediate external financing requirements. A further $3 billion deposit was also extended in the spring. However, the article argues that these arrangements provide temporary relief rather than long-term financial independence, particularly as regional conflict threatens the stability of the Gulf economies on which Pakistan relies. The report concludes that Pakistan faces a difficult balance between supporting Saudi Arabia militarily and preserving the financial and military resources needed to address its domestic and regional challenges.

Economic tide is turning in Bangladesh

If there is one thing that can bring some comfort to the struggling Bangladeshi economy, it is good relations with India. Bangladesh should remember that Delhi’s backing, through easy supplies of essentials

DP World Lands 15-Year Bangladesh Port Deal

The agreement between the Chittagong Port Authority (CPA) and DP World covers the New Mooring Container Terminal…reports Asian Lite News Desk Bangladesh has signed a 15-year concession agreement with global ports operator

Nepal Floods Cause $1.66 Billion In Damage, Says World Bank

Nepal’s August 2026 floods caused an estimated US$1.66 billion in direct physical damage, with infrastructure accounting for 83 per cent of the total…reports Asian Lite News Desk Nepal’s devastating floods in August 2026 caused an estimated US$1.66 billion in direct physical damage, with infrastructure accounting for 83 per cent of the total, according to a World Bank report. The estimate, included in the World Bank’s Nepal Development Update unveiled this week, is close to the Nepal government’s preliminary Rapid Damage and Needs Assessment (RDNA), which put physical damage at US$1.81 billion. The government’s assessment also estimated losses beyond physical assets at US$883.32 million, taking the total economic effects of the disaster to approximately US$2.7 billion. The World Bank’s Global Rapid Post-Disaster Damage Estimation (GRADE) found that infrastructure suffered the greatest damage, estimated at US$1.38 billion, or 83 per cent of the total. Residential buildings accounted for US$185 million, or 11 per cent, while non-residential buildings sustained damage worth US$101 million, or 6 per cent. The floods along the Bhotekoshi and Trishuli rivers caused extensive damage to hydropower projects, solar energy facilities, electricity transmission infrastructure and transport networks. The energy sector, particularly hydropower, was among the worst affected. The August 2026 floods affected 12 hydropower projects and one solar project, involving 281.1 MW of operational capacity and 395.02 MW of capacity under construction. Damage to transmission lines and substations also disrupted the transmission of 149.6 MW of electricity to the national grid. The total affected capacity reached approximately 430.7 MW, equivalent to 10.6 per cent of Nepal’s installed hydropower and solar capacity at the end of fiscal year 2025-26, which concluded in mid-July. The disaster also severely damaged transport infrastructure along the 82-km Rasuwa trade corridor, which connects Kathmandu with the Rasuwagadhi border point with China. More than 55 km of the corridor was damaged, including 40 km that was completely destroyed. The floods also damaged 37 motorable bridges and 68 suspension bridges. The disaster resulted in significant human losses along the affected corridor and beyond. According to Nepal’s National Disaster Risk Reduction and Management Authority, 1,455 people had been confirmed dead, while 5,285 remained missing following the disaster. The World Bank report found that the physical damage was concentrated in three districts in central Nepal: Rasuwa, Nuwakot and Dhading. Rasuwa was the worst-affected district, accounting for US$1.07 billion, or 64 per cent, of the total direct damage. Nuwakot recorded an estimated US$551 million in damage, while Dhading suffered approximately US$39 million. “The findings highlight the concentration of physical damage in a small number of districts and the disproportionate impact on infrastructure, underscoring the scale of the reconstruction challenge facing the affected areas,” the World Bank said. The global development financier said the floods had demonstrated the scale and complexity of disaster risks in Nepal’s Himalayan environment. The event also showed how a single extreme weather event could trigger cascading impacts across sectors and geographical areas. The report said recovery efforts should extend beyond restoring infrastructure to its pre-disaster condition. While the principle of “Build Back Better” remained relevant, the World Bank stressed that rebuilding infrastructure to higher engineering standards in the same locations might not always be sufficient. “In some cases, simply rebuilding the same infrastructure in the same location to a higher engineering standard may not be sufficient. Nepal may need to build differently — based on a better understanding of risk, more careful decisions about location and design, greater redundancy in critical networks, stronger monitoring and early warning, and a more integrated approach to infrastructure development in the Himalayas,” the report said. The World Bank said Nepal’s recovery strategy should incorporate improved risk assessment, more informed infrastructure planning, stronger monitoring systems and better early warning mechanisms. The report emphasised that reconstruction should not only restore damaged assets but also reduce the impact of future disasters, particularly in the country’s vulnerable Himalayan regions.
Go toTop