Gitanjali Gems topped the list of 25 wilful defaulters followed by Era Infra Engineering, Concast Steel and Power, REI Agro Ltd and ABG Shipyard Ltd…reports Asian Lite News
A recent Parliament reply disclosed that scheduled commercial banks have written off loans worth about Rs 10 lakh crore in the last five financial years.
According to a reply by the Finance Ministry, during 2021-22, the write-off amount came down to Rs 1,57,096 crore compared to Rs 2,02,781 crore in 2020-21.
As per the written reply by Minister of State for Finance, Bhagwat K. Karad in Rajya Sabha, during 2019-20, the write-off was worth Rs 2,34,170 crore, down from Rs 2,36,265 crore, the highest in five years recorded in 2018-19. During 2017-18, the write-off by banks stood at Rs 1,61,328 crore.
In all, bank loans to the tune of Rs 9,91,640 crore have been written off in the last five years — 2017-18 to 2021-22.
He also said that “scheduled commercial banks (SCBs) and all Indian financial institutions report certain credit information of all borrowers having aggregate credit exposure of Rs 5 crore and above to RBI under its Central Repository of Information on Large Credits database.
As per the data, the highest number of 2,840 wilful defaulters reported during 2020-21 was followed by 2,700 in 2021-22. The number of wilful defaulters stood at 2,207 at the end of March 2019 that rose to 2,469 in 2019-20.
Gitanjali Gems topped the list of 25 wilful defaulters followed by Era Infra Engineering, Concast Steel and Power, REI Agro Ltd and ABG Shipyard Ltd.
Similarly, Mehul Choksi’s company Gitanjali Gems owes banks a whopping Rs 7,110 crore while Era Infra Engineering owes Rs 5,879 crore and Concast Steel and Power Ltd Rs 4,107 crore.
Call for restructuring of loans
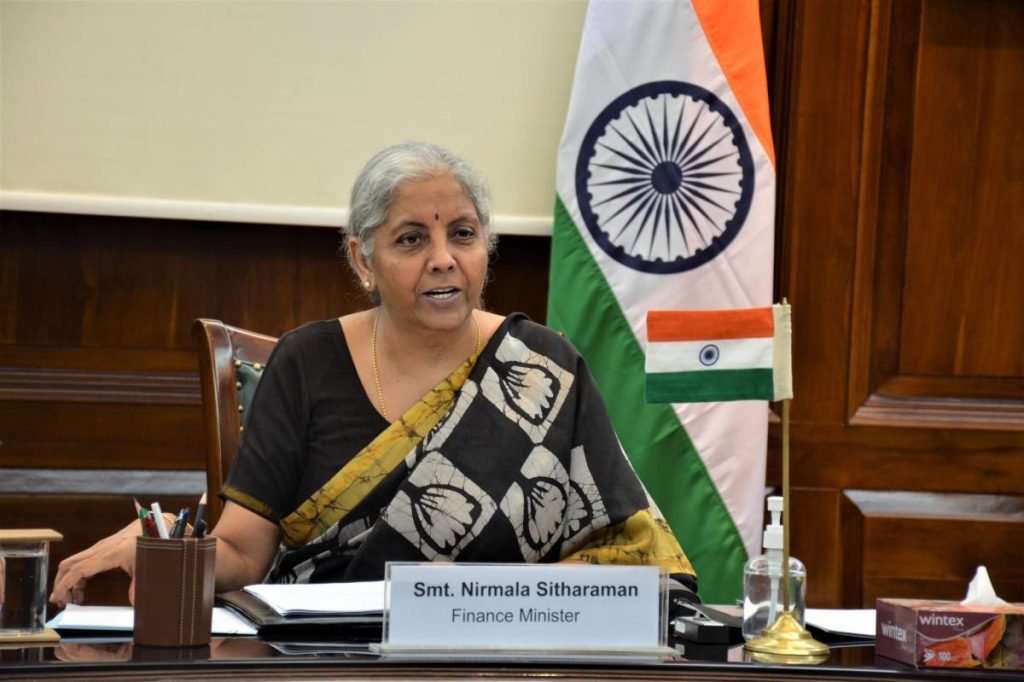
The Karnataka Registered Unaided Private Schools Management Association (RUPSA) has requested Union Finance Minister Niramala Sitharaman to consider restructuring of loans availed by private unaided schools in the state during Covid pandemic.
“For 2 years, private schools have been struggling to balance their financial commitments. Public statements given by politicians and Education Department officials to gain brownie points have further jeopardised our situation,” RUPSA President Lokesh Talikatte said in the letter sent to the Union Finance Ministry.
“The aftermath of this is that private schools are not able to receive fees dues from the parents. Thus we are not able to repay our loan installments and service interest on loans. Our dues are piling up and we are in debt trap,” he added.
Adding insult to injury, expenses like increased electric bills, building tax, and fire safety expenses have further aggravated the situation, he said.
“In the past two and half years, around two and a half thousand schools have either closed or are at the verge of closing. If the situation continues, many more private schools will close and thousands of employees depending on these schools will be jobless,” Talikatte warned.
“Therefore, in this critical situation, we need your (Sitharaman) intervention. Please order for restructuring of loans availed by private schools from nationalised banks, scheduled banks, NBFCs, co-operative banks etc. We need a moratorium of one year at least. Your favorable decision in this regard will be immensely helpful in uplifting the education system. We request you to consider our request at the earliest,” he said.
Talikatte said that the pandemic has shattered the economic situation of many sectors in the world, and the worst affected is the education sector because the children have not only lost their two and half years learning but also have gone under depression. This is very difficult to deal with and compensate for, he noted.
He contended that private unaided schools are shouldering the responsibilities of the state government in improving the education system. “Madam, our contribution is, though not more but definitely equivalent to government efforts,” he said.