July 16, 2024
4 mins read

G20 Presidency Drives Global Digital Public Infrastructure Agenda

In Part 3 of the report, a forward-looking perspective is presented, outlining a strategic blueprint for elevating DPI across various sectors, as well as on a global scale through a range of its policy recommendations…reports Asian Lite News

The final report of India’s G20 Task Force on Digital Public Infrastructure aimed at strengthening the foundations of DPI worldwide, especially the Global South, was released here on Monday 

The work of this Task Force had led to the acceptance of the definition and framework of the Digital Public Infrastructure (DPI) during India’s G20 Presidency and will be taken forward for implementation during the Brazilian and South African Presidencies.

The report will play a key role in defining the future course of the DPI approach and actions for implementation around the globe, particularly in the Global South, according to a Finance Ministry statement.

The task force was led by the co-Chairs —  Amitabh Kant, G20 Sherpa of India and Nandan Nilekani, co-founder and chairman of Infosys and the Founding Chairman of UIDAI (Aadhaar).

The complete report is available on the website of the Department of Economic Affairs, Ministry of Finance.

On the occasion of releasing the report, Amitabh Kant said: “India did an incredible pole vault in Digital Public Infrastructure. We achieved in 9 years what would have taken 50 years without DPI. Today in India, UPI is used at all levels from street vendors to large shopping malls, with the highest percentage of digital transactions globally, accounting for nearly 46 per cent share. All these proved to be building blocks for India to steer through the COVID-19 pandemic, be it transfer $4.5 billion into the bank accounts of 160 million beneficiaries or facilitate distribution of 2.5 million vaccinations in two years with digital vaccine certificates on mobiles. We are far advanced in terms of digitisation and I am confident, this report will be the guiding North Star for the world to follow.”

Co-Chair of the Task Force Nandan Nilekani said: “Governments and businesses around the world are increasingly realising that if they really want to achieve SDGs (sustainable development goals) and social goals like inclusive growth, it has to have underlying DPI to make that happen. DPI has the power to dramatically improve the lives of citizens and transform governance.”

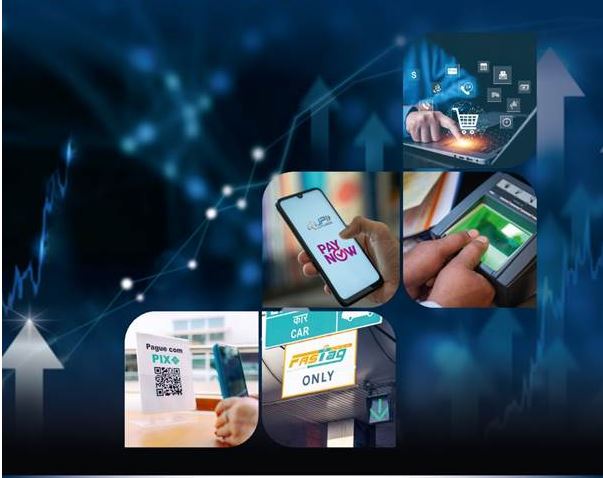
India’s G20 Presidency provided a significant opportunity to set and drive the global policy discourse on key economic and developmental agenda. India’s digital public infrastructure (DPI) – digital identity, fast payment system along with consent-based data sharing – has demonstrated how 1.4 billion individuals can access socio-economically important services in the fields of finance, health, education, e-Governance, taxation, skills etc.

India’s achievements in the field of DPI and also could gather unanimous support from all G20 members on DPI-related reports and deliverables under both Finance Track and Sherpa Tracks, the Finance Ministry added.

The report encompasses three essential parts that collectively unravel the approach for global DPI advancement and adoption. In Part 1, the DPI Approach emerges as a transformative paradigm that effectively addresses global challenges through innovative technological solutions.

In Part 2 of the report delves into how India has steered its DPI agenda, especially during its G20 Presidency in 2023 under its various working groups. 

In Part 3 of the report, a forward-looking perspective is presented, outlining a strategic blueprint for elevating DPI across various sectors, as well as on a global scale through a range of its policy recommendations.

The report also highlights the need to identify an existing body of global standards with the scope of multinational presence, to foster and harness the DPI ecosystem across various regions and countries, especially Global South countries.

‘India Needs Robust Sovereign Credit Rating Agencies’

As India embarks on its journey to become ‘Viksit Bharat’ by 2047, it’s important that we have appropriate credit ratings and call out global agencies for biases and lack of transparency for not objectively assessing India’s strong economic fundamentals, G20 Sherpa and former NITI Aayog CEO, Amitabh Kant, said on Saturday. 

Addressing the CareEdge Ratings ‘Conversations 2024’ conference in Pune, he said the notion that developing countries offer more risky investments is not solely based on objective financial metrics but is significantly influenced by subjective assessment.

Kant stressed the need for promoting home-grown credit ratings agencies, saying that appropriate sovereign credit ratings are actually a very critical issue that impacts not only India but also the entire emerging economies.

Hailing India’s high growth rate of around 8.2 per cent, he stressed that future growth will come from cutting-edge areas.

According to Najib Shah, Chairman, CareEdge, the world is moving away from domination by a single superpower, a single currency and moving towards a more balanced and complex system that’s emerging and evolving.

“Such an environment also has implications for the financial situation. Destructive competition between the US and China has ushered in a new era of competing geopolitics and economies. The role of the credit rating agency will be important here for acting in a transparent, competitive, professional manner,” Shah told the gathering.

At the event, Gulshan Malik, Deputy Managing Director, State Bank of India (SBI) said the banking sector in India is adequately capitalised as well as ready to fund the next phase of growth which is very critical.
ALSO READ-UAE participates in 3rd G20 Sherpas Meeting

Previous Story

Tories received £50,000 donation from Hinduja group

Next Story

Cong slams govt over 8 crore new jobs claim

Previous Story

Tories received £50,000 donation from Hinduja group

Next Story

Cong slams govt over 8 crore new jobs claim

Latest from -Top News

Pakistan Risks Overstretching Itself in Yemen War

Pakistan’s expanding military role in Saudi Arabia amid the Yemen conflict could strain its defence resources and fragile finances…reports Asian Lite News Desk Pakistan’s military involvement in the war in Yemen may prove unsustainable because of mounting financial pressures and competing security demands, according to a new report. Islamabad’s growing military presence in Saudi Arabia risks stretching its defence resources while exposing the country to greater strategic and economic challenges. An article by Andrew Wilson in One World Outlook describes Pakistan’s involvement as a case of “fiscal and strategic overreach”, arguing that the country lacks the financial flexibility to sustain an expanded military commitment. Pakistan’s external finances depend heavily on an International Monetary Fund (IMF) programme, financial support from Gulf countries and remittances from Pakistani workers in the region. The report argues that deeper military involvement in the conflict could place additional pressure on these sources of financial stability. It also warns that deploying troops and military equipment abroad could weaken Pakistan’s capacity to address security challenges along its eastern border and deal with two domestic insurgencies. The move could also draw Islamabad into a conflict it has sought to approach cautiously. A Reuters report in May, citing Pakistani security and government sources, said Islamabad had deployed around 8,000 troops, a squadron of approximately 16 aircraft, mostly JF-17 fighter jets, two drone squadrons and a Chinese HQ-9 air-defence battery to Saudi Arabia. According to those sources, Riyadh was financing the deployment, with Pakistani personnel operating the equipment. The sources also said a confidential agreement contemplated the possibility of deploying up to 80,000 troops. Islamabad has not confirmed those figures, although it has acknowledged its military presence in Saudi Arabia, including the deployment of fighter jets at King Abdulaziz Air Base from April. The One World Outlook article argues that Saudi financial support can cover allowances and operating expenses but cannot easily replace military equipment needed elsewhere or resolve the political and strategic challenges of participating in the Yemen conflict. Pakistan’s defence budget is another concern. For the 2026-27 financial year, the federal government allocated PKR 3 trillion, or approximately $10.8 billion, to defence services. The allocation represents an 18 per cent increase from the original PKR 2.55 trillion provision and amounts to around 2.1 per cent of projected gross domestic product (GDP). Defence spending accounts for approximately 16 per cent of the federal government’s PKR 18.8 trillion expenditure. Military pensions are budgeted separately at PKR 822 billion, while debt servicing costs stand at approximately PKR 8 trillion, more than two-and-a-half times the defence allocation. The report argues that these competing financial obligations leave little room for additional military expenditure without placing further pressure on public finances. Pakistan’s reliance on IMF assistance also limits its fiscal flexibility. The country must meet the conditions attached to the programme, including a primary budget surplus target of 2 per cent of GDP and continued restraint on development spending. According to the article, these requirements make it difficult for Islamabad to finance an additional military commitment without compromising other budgetary priorities. Pakistan’s economic indicators offer limited reassurance. Economic growth for the 2025-26 financial year is estimated at between 3.6 and 3.7 per cent, while inflation reached approximately 10.3 per cent in September following an energy price shock. Foreign exchange reserves stood at around $21.5 billion at the end of September. Although this marks an improvement from the low levels recorded in 2023, the report notes that the reserves cover only a few months of imports. Financial assistance from Gulf partners remains central to Pakistan’s external stability. The article says Islamabad holds approximately $8 billion in Saudi deposits at its central bank. In July, the State Bank of Pakistan said Riyadh had extended the maturity of $5 billion in deposits to December 2028, easing the country’s immediate external financing requirements. A further $3 billion deposit was also extended in the spring. However, the article argues that these arrangements provide temporary relief rather than long-term financial independence, particularly as regional conflict threatens the stability of the Gulf economies on which Pakistan relies. The report concludes that Pakistan faces a difficult balance between supporting Saudi Arabia militarily and preserving the financial and military resources needed to address its domestic and regional challenges.

UK and Germany Ratify Kensington Treaty

Britain and Germany ratify the Kensington Treaty, agreeing new cooperation on AI, quantum research, defence and security while targeting investment, jobs and Russian hybrid threats…reports Asian Lite News Desk Britain and Germany

Economic tide is turning in Bangladesh

If there is one thing that can bring some comfort to the struggling Bangladeshi economy, it is good relations with India. Bangladesh should remember that Delhi’s backing, through easy supplies of essentials

DP World Lands 15-Year Bangladesh Port Deal

The agreement between the Chittagong Port Authority (CPA) and DP World covers the New Mooring Container Terminal…reports Asian Lite News Desk Bangladesh has signed a 15-year concession agreement with global ports operator
Go toTop

Don't Miss

Fake call centre duping foreigners busted in Delhi

The accused were extorting Amazon customers based in the US

Washington’s special envoy Uzra Zeya to visit India

In India, she will meet with senior government officials to