The US-China tariff war has reshaped global trade, pushing exporters to seek new markets as bilateral shipments decline….reports Asian Lite News Desk
The US-China tariff war has sharply reduced bilateral trade, with Chinese exports to the United States falling 22 per cent and American exports to China declining 25 per cent between February 2025 and January 2026, according to the International Monetary Fund (IMF). However, businesses in both countries have redirected shipments to alternative markets, particularly in Asia, cushioning much of the immediate impact of higher trade barriers.
In its October 2026 World Economic Outlook, released on Tuesday, the IMF said the decline in bilateral trade reduced China’s total export growth by 3.3 percentage points and that of the United States by 1.7 percentage points.
Despite the setbacks, exporters in both countries expanded shipments to other destinations, helping keep overall exports close to their pre-tariff growth trajectories.
By January 2026, Chinese exports to markets outside the United States were 4.7 percentage points above their pre-tariff trend. American exports to destinations other than China were 2.6 percentage points above their earlier trend.
These adjustments kept total exports from both countries within approximately one percentage point of their respective pre-tariff trajectories, highlighting businesses’ ability to adapt to changing trade conditions.
The IMF examined how companies redirected shipments following the tariff increases introduced in 2025. Its analysis found that Chinese exports of products affected by US tariffs to alternative markets increased by an amount equivalent to 52 per cent of the trade at risk within a year.
After adjusting for export growth that would likely have occurred without the tariffs, the IMF estimated that trade diversion attributable to the tariff measures amounted to 39 per cent of the trade at risk.
The corresponding figures for American exports affected by Chinese retaliatory tariffs were considerably lower. US shipments of these products to third markets increased by an amount equivalent to 17 per cent of the trade at risk, with only about 7 per cent attributable to the tariff shock after accounting for existing trends.
The IMF partly attributed the difference to the countries’ varying dependence on each other’s markets before the escalation in tariffs. The United States accounted for approximately 15 per cent of Chinese exports before the tariff increases, while China represented around 7 per cent of American exports.
Asia emerges as key beneficiary
Emerging and advanced Asian economies absorbed approximately half of the trade redirected from the US-China bilateral relationship, making the region the principal beneficiary of the changing trade patterns.
The European Union received nearly one-fifth of the diverted trade, while smaller shares went to the Middle East, Central Asia, Africa and the Western Hemisphere.
The composition of redirected shipments varied across regions. Electrical machinery accounted for a substantial share of increased exports to Asian markets, while vehicles featured prominently in shipments redirected to the Middle East and Central Asia.
The findings indicate that businesses have adjusted production and distribution networks to navigate higher trade barriers, shifting goods towards markets where demand and trading conditions remain favourable.
However, the IMF cautioned that redirecting exports cannot fully eliminate the longer-term economic costs of protectionism.
Sustained trade restrictions could raise operating costs, encourage the duplication of production facilities and reduce efficiency across global supply chains. Such changes could also weaken the benefits of international specialisation and increase the costs of doing business.
Global trade growth faces slowdown
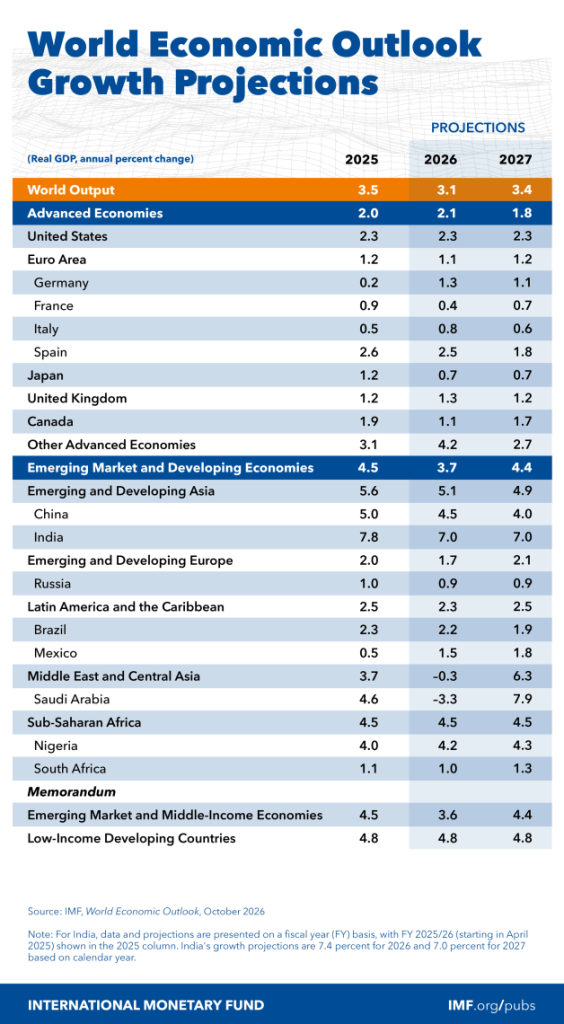
The IMF projected global trade volume growth to slow from 5 per cent in 2025 to 4.6 per cent in 2026 before edging up to 4.7 per cent in 2027.
The outlook reflects continuing adjustments in international trade alongside wider economic pressures. Although businesses have found alternative markets, the Fund’s analysis suggests that the resilience of individual exporters does not necessarily remove the broader costs associated with trade fragmentation.
The report also highlighted new bilateral and regional trade arrangements, including agreements involving India and the European Union and the United Kingdom, as potential avenues for reducing trade barriers and strengthening supply-chain resilience.
The October 2026 World Economic Outlook examines the consequences of trade restrictions alongside other major developments affecting the global economy, including commodity prices, the Middle East conflict and the boom in global investment in artificial intelligence.
The IMF’s assessment underscores the distinction between businesses adapting to tariffs in the short term and the wider economic consequences of prolonged restrictions on international commerce.