January 24, 2025
2 mins read

UAE’s near-term growth strong, says IMF 

The Fund highlighted that the UAE banks’ exposure to the real estate sector has declined by 4 percentage points to 19.6 during the period December 2021 to September 2024…reports Asian Lite News

The International Monetary Fund expected UAE’s near-term growth to remain healthy at around 4 percent in 2025, despite lower-than-expected oil production related to OPEC+ agreements. 

This came in a statement issued by the IMF at the conclusion of a staff visit to the UAE to discuss economic and financial developments, the outlook and the country’s policy and reform priorities. 

“Near-term growth is strong and expected to remain healthy at around 4 percent in 2025, despite lower-than-expected oil production related to OPEC+ agreements. Non-hydrocarbon activity is boosted by tourism, construction, public expenditure, and continued growth in financial services. Capital inflows remain strong, attracted by social and business-friendly reforms, and contribute to ongoing demand for real estate, which is driving further growth in house prices across different segments and locations. Hydrocarbon GDP is expected to grow above 2.0 percent this year, following OPEC+ decisions to sustain production cuts, and as the UAE implements a more gradual OPEC+ quota increase. Inflation is expected to remain contained around 2.0 percent in 2025 despite higher housing and utilities-related costs,” reads the statement. 

The statement expected hydrocarbon revenue to decline amid volatile oil prices and reduced oil production, “but fiscal and external surpluses are projected to remain comfortable. The fiscal surplus is expected to moderate to around 4 percent of GDP in 2025 from an estimated 5 percent of GDP last year. However, non-hydrocarbon revenue is projected to increase steadily in the coming years with the ongoing implementation of the corporate income tax. Public debt remains contained at around 30 percent of GDP. The current account surplus is projected at around 7.5 percent of GDP, while international reserves are healthy at over 8.5 months of imports.” 

It expected the UAE banks to remain adequately capitalised and liquid overall, “while asset quality further improved in 2024. Robust domestic activity and resilient demand for credit has supported banks’ profitability amid still-elevated interest rates.” 

The Fund highlighted that the UAE banks’ exposure to the real estate sector has declined by 4 percentage points to 19.6 during the period December 2021 to September 2024, and risks associated with continued increasing house prices should continue to be closely monitored. 

The IMF hailed the UAE reform efforts as supportive of medium-term growth and a smooth energy transition, with prioritisation and sequencing key to ensure effective outcomes. “Ongoing infrastructure investments should enhance tourism and domestic activity, while ongoing trade liberalisation, underpinned by Comprehensive Economic Partnership Agreements, should further boost trade and FDI. Advancing a medium-term fiscal framework would ensure a coordinated national fiscal stance, promote long-term sustainability, and help meet climate change-related challenges. Continued progress in improving economic data collection and dissemination will reinforce these efforts.” 

ALSO READ: UAE experts stress urgency of cyber defences 
Previous Story

e& Named Fastest Growing Brand Globally 

Next Story

Sharjah Literature Festival concludes inaugural edition V

Previous Story

e& Named Fastest Growing Brand Globally 

Next Story

Sharjah Literature Festival concludes inaugural edition V

Latest from -Top News

Pakistan Risks Overstretching Itself in Yemen War

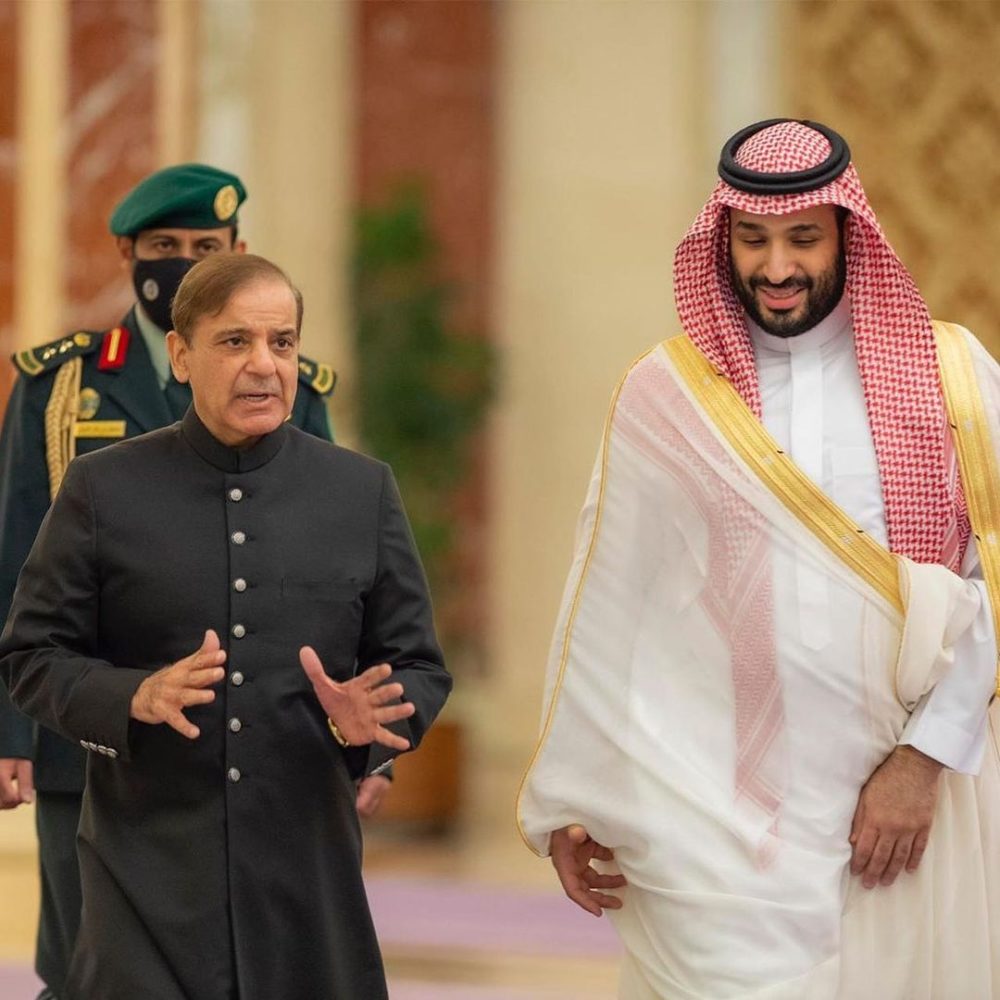
Pakistan’s expanding military role in Saudi Arabia amid the Yemen conflict could strain its defence resources and fragile finances…reports Asian Lite News Desk Pakistan’s military involvement in the war in Yemen may prove unsustainable because of mounting financial pressures and competing security demands, according to a new report. Islamabad’s growing military presence in Saudi Arabia risks stretching its defence resources while exposing the country to greater strategic and economic challenges. An article by Andrew Wilson in One World Outlook describes Pakistan’s involvement as a case of “fiscal and strategic overreach”, arguing that the country lacks the financial flexibility to sustain an expanded military commitment. Pakistan’s external finances depend heavily on an International Monetary Fund (IMF) programme, financial support from Gulf countries and remittances from Pakistani workers in the region. The report argues that deeper military involvement in the conflict could place additional pressure on these sources of financial stability. It also warns that deploying troops and military equipment abroad could weaken Pakistan’s capacity to address security challenges along its eastern border and deal with two domestic insurgencies. The move could also draw Islamabad into a conflict it has sought to approach cautiously. A Reuters report in May, citing Pakistani security and government sources, said Islamabad had deployed around 8,000 troops, a squadron of approximately 16 aircraft, mostly JF-17 fighter jets, two drone squadrons and a Chinese HQ-9 air-defence battery to Saudi Arabia. According to those sources, Riyadh was financing the deployment, with Pakistani personnel operating the equipment. The sources also said a confidential agreement contemplated the possibility of deploying up to 80,000 troops. Islamabad has not confirmed those figures, although it has acknowledged its military presence in Saudi Arabia, including the deployment of fighter jets at King Abdulaziz Air Base from April. The One World Outlook article argues that Saudi financial support can cover allowances and operating expenses but cannot easily replace military equipment needed elsewhere or resolve the political and strategic challenges of participating in the Yemen conflict. Pakistan’s defence budget is another concern. For the 2026-27 financial year, the federal government allocated PKR 3 trillion, or approximately $10.8 billion, to defence services. The allocation represents an 18 per cent increase from the original PKR 2.55 trillion provision and amounts to around 2.1 per cent of projected gross domestic product (GDP). Defence spending accounts for approximately 16 per cent of the federal government’s PKR 18.8 trillion expenditure. Military pensions are budgeted separately at PKR 822 billion, while debt servicing costs stand at approximately PKR 8 trillion, more than two-and-a-half times the defence allocation. The report argues that these competing financial obligations leave little room for additional military expenditure without placing further pressure on public finances. Pakistan’s reliance on IMF assistance also limits its fiscal flexibility. The country must meet the conditions attached to the programme, including a primary budget surplus target of 2 per cent of GDP and continued restraint on development spending. According to the article, these requirements make it difficult for Islamabad to finance an additional military commitment without compromising other budgetary priorities. Pakistan’s economic indicators offer limited reassurance. Economic growth for the 2025-26 financial year is estimated at between 3.6 and 3.7 per cent, while inflation reached approximately 10.3 per cent in September following an energy price shock. Foreign exchange reserves stood at around $21.5 billion at the end of September. Although this marks an improvement from the low levels recorded in 2023, the report notes that the reserves cover only a few months of imports. Financial assistance from Gulf partners remains central to Pakistan’s external stability. The article says Islamabad holds approximately $8 billion in Saudi deposits at its central bank. In July, the State Bank of Pakistan said Riyadh had extended the maturity of $5 billion in deposits to December 2028, easing the country’s immediate external financing requirements. A further $3 billion deposit was also extended in the spring. However, the article argues that these arrangements provide temporary relief rather than long-term financial independence, particularly as regional conflict threatens the stability of the Gulf economies on which Pakistan relies. The report concludes that Pakistan faces a difficult balance between supporting Saudi Arabia militarily and preserving the financial and military resources needed to address its domestic and regional challenges.
Go toTop

Don't Miss

TCL Electronics joins Jashanmal  

TCL Electronics (1070.HK), the global No.2 LCD TV brand and

London forum boosts UAE trade links

The forum also showcased the Abu Dhabi Chamber’s three-year roadmap,