September 3, 2021
3 mins read

UK To Invest $1.2 Bn For Green Projects In India

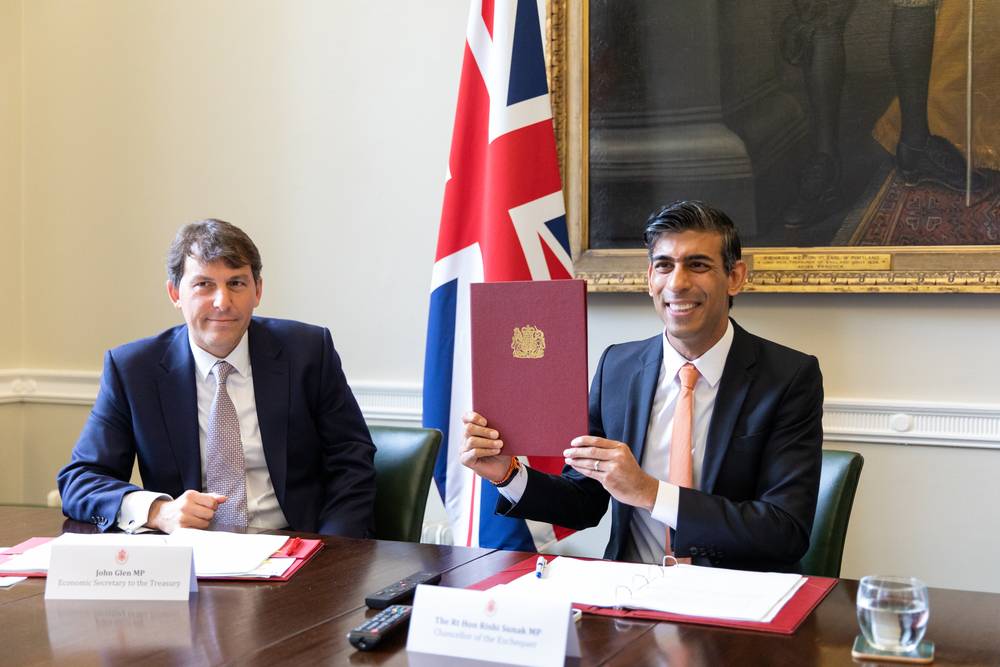
Rishi Sunak and Nirmala Sitharaman announced the joint launch of the Climate Finance Leadership Initiative (CFLI) India partnership to mobilise private capital into sustainable infrastructure in India, reports Asian Lite Newsdesk

Chancellor Rishi Sunak and India’s Finance Minister Nirmala Sitharaman announced new steps to boost investment and tackle climate change at the 11th Economic and Financial Dialogue (EFD) between the UK and India held on Thursday.

The UK government announced a USD 1.2 billion package for public and private investment in green projects and renewable energy, and the launch of the Climate Finance Leadership Initiative (CFLI) India partnership, the official statement said on Thursday.

The investments will support India’s target of 450GW renewable energy by 2030.

At EFD, Sitharaman and Rishi Sunak also agreed to be ambitious when considering services in the upcoming UK-India trade negotiations, which could open up new opportunities for UK financial firms and help more Indian companies to access finance in London. Services account for 71% of UK GDP, and 54% of Indian GDP, the press release added.

UK Chancellor of the Exchequer Rishi Sunak, said, “The UK and India already have strong ties, and today we’ve made important new agreements to boost our relationship and deliver for both our countries. Supporting India’s green growth is a shared priority so I’m pleased that we’ve announced a USD 1.2 billion investment package, and launched the new CFLI India partnership to boost investment in sustainable projects in India as the UK gears up to host COP26. With trade negotiations also coming up, our agreement to be ambitious when considering services will create new opportunities in both markets, supporting jobs and investment in the UK and India.”
The UK-India economic relationship is already strong with bilateral trade of over £18bn in 2020, supporting nearly half a million jobs in each other’s economies.

British High Commissioner to India Alex Ellis said, “The economic and financial dialogue between Finance Ministers is another step towards realising the ambition agreed between Prime Ministers Johnson and PM Modi in the 2030 bilateral roadmap, especially with the COP26 climate conference starting in Glasgow in two months to tackle climate change. Today’s discussions and agreements show what closer economic and financial ties between the UK and India can offer.”

The dialogue agreed upon a $1bn investment from CDC, the UK’s development finance institution in green projects in India between 2022-2026. It builds on CDC’s USD 1.99 billion existing portfolios of private sector investments in India, the press release said.

The UK also welcomed India’s recent decision to lift the Foreign Direct Investment cap in the insurance sector from 49% to 74% which will help British firms to take greater ownership of their operations in India.

New cooperation under the UK-India Infrastructure Partnership with the UK’s Infrastructure Projects Authority was agreed to support India’s ambitious National Infrastructure Pipeline project.

Earlier this year, Prime Minister Narendra Modi and his British counterpart Boris Johnson launched the UK-India 2030 Roadmap to bring the economies and people closer together over the next decade and boost cooperation in areas that matter to both countries. The countries have also set out an ambitious goal to double trade by 2030, including through negotiating a Free Trade Agreement. (ANI)

ALSO READ-Biden meets Ukrainian president over security issues, ties

READ MORE-UK records highest daily Covid death toll since March

Previous Story

‘Catastrophe’ : Russia on US presence in Afghanistan

Next Story

An experience of digital fragrance

Previous Story

‘Catastrophe’ : Russia on US presence in Afghanistan

Next Story

An experience of digital fragrance

Latest from -Top News

Pakistan Risks Overstretching Itself in Yemen War

Pakistan’s expanding military role in Saudi Arabia amid the Yemen conflict could strain its defence resources and fragile finances…reports Asian Lite News Desk Pakistan’s military involvement in the war in Yemen may prove unsustainable because of mounting financial pressures and competing security demands, according to a new report. Islamabad’s growing military presence in Saudi Arabia risks stretching its defence resources while exposing the country to greater strategic and economic challenges. An article by Andrew Wilson in One World Outlook describes Pakistan’s involvement as a case of “fiscal and strategic overreach”, arguing that the country lacks the financial flexibility to sustain an expanded military commitment. Pakistan’s external finances depend heavily on an International Monetary Fund (IMF) programme, financial support from Gulf countries and remittances from Pakistani workers in the region. The report argues that deeper military involvement in the conflict could place additional pressure on these sources of financial stability. It also warns that deploying troops and military equipment abroad could weaken Pakistan’s capacity to address security challenges along its eastern border and deal with two domestic insurgencies. The move could also draw Islamabad into a conflict it has sought to approach cautiously. A Reuters report in May, citing Pakistani security and government sources, said Islamabad had deployed around 8,000 troops, a squadron of approximately 16 aircraft, mostly JF-17 fighter jets, two drone squadrons and a Chinese HQ-9 air-defence battery to Saudi Arabia. According to those sources, Riyadh was financing the deployment, with Pakistani personnel operating the equipment. The sources also said a confidential agreement contemplated the possibility of deploying up to 80,000 troops. Islamabad has not confirmed those figures, although it has acknowledged its military presence in Saudi Arabia, including the deployment of fighter jets at King Abdulaziz Air Base from April. The One World Outlook article argues that Saudi financial support can cover allowances and operating expenses but cannot easily replace military equipment needed elsewhere or resolve the political and strategic challenges of participating in the Yemen conflict. Pakistan’s defence budget is another concern. For the 2026-27 financial year, the federal government allocated PKR 3 trillion, or approximately $10.8 billion, to defence services. The allocation represents an 18 per cent increase from the original PKR 2.55 trillion provision and amounts to around 2.1 per cent of projected gross domestic product (GDP). Defence spending accounts for approximately 16 per cent of the federal government’s PKR 18.8 trillion expenditure. Military pensions are budgeted separately at PKR 822 billion, while debt servicing costs stand at approximately PKR 8 trillion, more than two-and-a-half times the defence allocation. The report argues that these competing financial obligations leave little room for additional military expenditure without placing further pressure on public finances. Pakistan’s reliance on IMF assistance also limits its fiscal flexibility. The country must meet the conditions attached to the programme, including a primary budget surplus target of 2 per cent of GDP and continued restraint on development spending. According to the article, these requirements make it difficult for Islamabad to finance an additional military commitment without compromising other budgetary priorities. Pakistan’s economic indicators offer limited reassurance. Economic growth for the 2025-26 financial year is estimated at between 3.6 and 3.7 per cent, while inflation reached approximately 10.3 per cent in September following an energy price shock. Foreign exchange reserves stood at around $21.5 billion at the end of September. Although this marks an improvement from the low levels recorded in 2023, the report notes that the reserves cover only a few months of imports. Financial assistance from Gulf partners remains central to Pakistan’s external stability. The article says Islamabad holds approximately $8 billion in Saudi deposits at its central bank. In July, the State Bank of Pakistan said Riyadh had extended the maturity of $5 billion in deposits to December 2028, easing the country’s immediate external financing requirements. A further $3 billion deposit was also extended in the spring. However, the article argues that these arrangements provide temporary relief rather than long-term financial independence, particularly as regional conflict threatens the stability of the Gulf economies on which Pakistan relies. The report concludes that Pakistan faces a difficult balance between supporting Saudi Arabia militarily and preserving the financial and military resources needed to address its domestic and regional challenges.
Go toTop