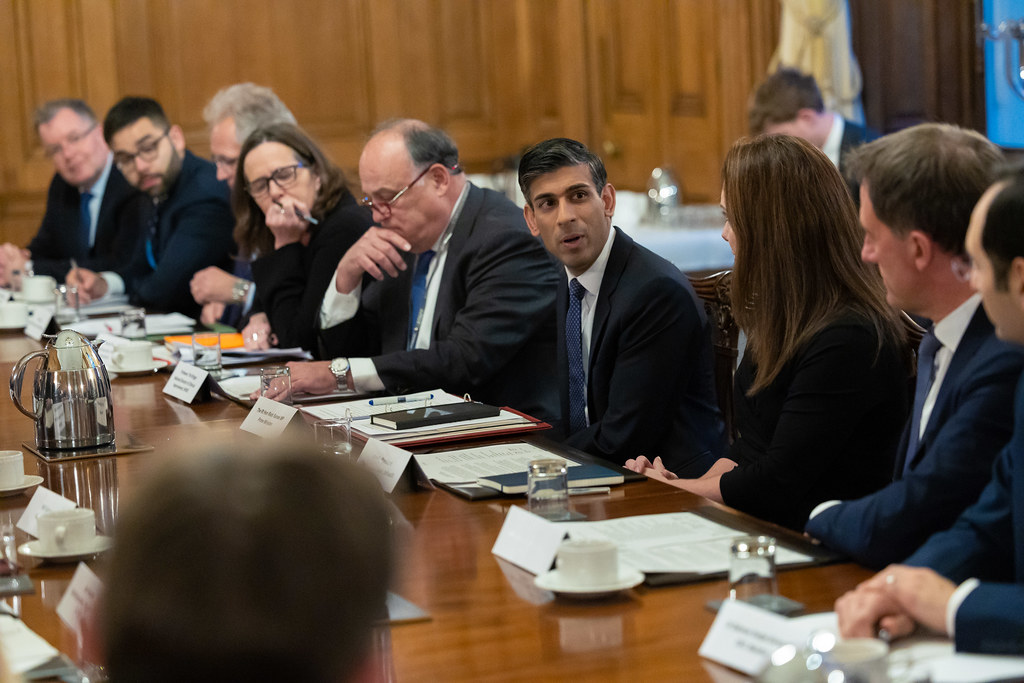
Hunt will announce a review of the system as one of 30 reforms to financial services regulation to be launched in Edinburgh…reports Asian Lite News
Chancellor Jeremy Hunt is to overhaul the “senior managers’ regime” — rules introduced in response to the 2008 financial crisis that “terrified” senior bankers and held them personally responsible for infractions on their watch.
Hunt will announce a review of the system as one of 30 reforms to financial services regulation to be launched in Edinburgh on Friday, according to people briefed on the plan.
The regime has since 2016 forced senior executives at banks, building societies and credit unions to take personal responsibility for infractions if they had not taken “reasonable steps” to prevent them. Penalties range from fines to bans.
New laws were introduced simultaneously which made it a criminal offence, punishable by up to seven years’ imprisonment and unlimited fines, for senior managers of lenders and major investment firms to cause a bank failure.
Ministers have insisted that Hunt’s “Edinburgh Reforms” will not mark a return to the risky practices that contributed to the 2008 crash and that Britain’s regulatory framework will remain rigorous.
One ally of the chancellor said the senior managers’ regime was seen as too onerous and would be reviewed. “We will introduce an agile but proportionate regulatory framework,” he said. “But we will maintain the high standards for which we are known around the world.”
Described by the Bank of England as a “critical element of the post-crisis reform agenda”, the senior managers’ regime was designed to ensure bankers had “nowhere to hide” for failings on their watch, as the public balked at the lack of accountability for collapses that cost taxpayers tens of billions of pounds.
Hunt will say on Friday that the regime will be reviewed by regulators and the government early next year, according to people familiar with the matter.
The Treasury declined to comment.
By the end of 2019, the rules had been expanded from covering the UK’s lenders to more than 47,000 companies across the City of London.
But while the financial services industry lambasted the rules as being a dead hand on recruitment, enforcement has so far been sparse.
In one of the few penalties issued by regulators, Jes Staley, Barclays’ then chief executive, was fined £640,000 in 2018 for trying to uncover the identity of an anonymous whistleblower.
Several of the key proposals in the Edinburgh Reforms will seek to unwind some of the more constraining features of regulations put in place after the 2008 crash, including loosening “ringfencing” rules for banks.
Hunt has already announced the removal of the cap on bankers’ bonuses and will also order a review of Mifid II, EU legislation that sought to strengthen protection for investors and transparency in financial markets.
City executives have long complained about the red tape imposed by post-crash regulations, but they have also since overhauled their businesses to cope with the demands. Such restructuring means that any reforms to regulations could take some time to lead to changes in how banks and corporate brokers operate.
London’s position as the pre-eminent European financial centre has been dented in recent years. London briefly lost its long-time crown of most valuable European stock market to Paris before gains in the pound pushed it narrowly back ahead, while Amsterdam took the title of busiest European share dealing centre.
Leading hedge fund manager Sir Paul Marshall of Marshall Wace recently described the London financial markets as a “Jurassic Park” of old-fashioned companies and investors, and it has struggled to attract the world’s fastest growing companies to list on UK exchanges, often losing out to New York, Shanghai or even Amsterdam.
Labour politicians have criticised the scrapping of the bonus cap and said the UK should not engage in a regulatory race to the bottom, but the government will insist the reforms strike the right balance between stability and innovation.
Others will say that in loosening regulation we risk forgetting the lessons of the financial crisis when excessive risk taking ended in billions in bailouts and a decade of stagnating productivity.
ALSO READ-UK kicks off process to negotiate new trade deal with South Korea