March 24, 2026
3 mins read

West Asia Fallout Slows Southeast Asia Growth

ASEAN-6 growth forecasts cut as West Asia conflict drives energy price surge, raises inflation risks and strains economies dependent on imported oil and gas supplies, reports Asian Lite Newsdesk

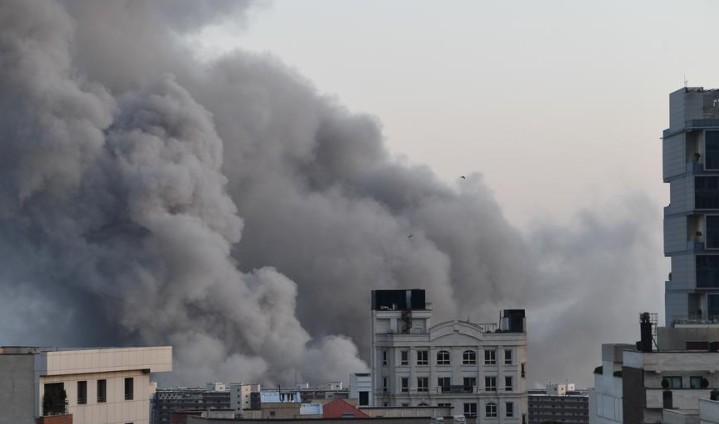
Economic growth forecasts across Southeast Asia have been downgraded as the escalating conflict in West Asia sends shockwaves through global energy markets, raising costs and straining economies heavily dependent on imported fuel.

Economists have revised the GDP outlook for the ASEAN-6 bloc — comprising Indonesia, Singapore, Thailand, Vietnam, the Philippines and Malaysia — cutting projections to 4.5 per cent for 2026, down from an earlier estimate of 4.8 per cent. Growth for 2027 has also been lowered slightly to 4.7 per cent.

The downgrades reflect mounting concerns over surging energy prices and disruptions to commodity supply chains, both of which are expected to weigh heavily on the region’s economic momentum. According to analysts, the impact is particularly pronounced for countries such as the Philippines and Vietnam, which have seen their growth forecasts reduced by 0.4 percentage points, while Thailand’s outlook has been cut by 0.3 percentage points.

In a recent research note, Maybank Investment Bank said in third-person remarks that the ongoing energy shock would have a broad negative effect on most ASEAN economies, given their reliance on imported oil and gas. The report highlighted that rising fuel costs are likely to erode purchasing power, increase production expenses and dampen overall economic activity.

Malaysia, however, stands out as a relative exception. As a net exporter of energy, it is expected to be better insulated from the immediate impact of higher oil and gas prices, potentially cushioning the broader regional slowdown.

The ripple effects of the crisis are also being felt in inflation trends. Economists have raised their inflation forecasts for the ASEAN-6 to 2.7 per cent for both 2026 and 2027, up from earlier estimates of 2.2 per cent and 2.5 per cent respectively. The sharpest upward revisions have been recorded in Thailand, the Philippines and Indonesia, where higher fuel costs are feeding into consumer prices more rapidly.

The surge in energy prices is expected to have wider macroeconomic implications. Analysts noted in third-person comments that increased import bills could weaken current account balances and put pressure on regional currencies, particularly in economies with limited domestic energy resources. At the same time, governments may face rising fiscal burdens as they attempt to shield consumers through subsidies and price controls.

Indonesia, for instance, could face significant fiscal challenges if elevated oil prices persist. Its legally mandated fiscal deficit ceiling of 3 per cent may come under strain, as authorities balance the need for economic stability with the rising cost of fuel subsidies. Similar pressures are expected in Thailand and Malaysia, where government spending could increase to mitigate the impact on households and businesses.

The energy shock has also disrupted the trajectory of monetary policy across the region. Central banks that had been considering easing measures to support growth may now be forced to reassess their stance in light of inflationary pressures. Economists said in third-person remarks that the surge in energy costs has effectively “short-circuited” the expected cycle of monetary easing.

Globally, the fallout from the West Asia conflict is being compared to some of the most severe energy crises in modern history. A senior official from the International Energy Agency recently warned that the scale of disruption is equivalent to the oil shocks of the 1970s combined with the 2022 gas crisis following Russia’s invasion of Ukraine.

In response, countries across Asia, Africa and Europe have begun implementing emergency measures to conserve fuel and maintain supply. These include fuel rationing, industrial slowdowns, additional public holidays and expanded work-from-home policies aimed at reducing energy consumption.

Newsdesk

Newsdesk

Aravind Rajeev is Deputy News Editor at Asian Lite, mostly covering the Middle East and GCC. He has over eight years of experience as a journalist, with a background in ground-level reporting, crime reporting, as well as international and regional news.

Previous Story

Firms Back Strong UK–Taiwan Ties

Next Story

Aditi Reinvents Saree Aesthetic

Previous Story

Firms Back Strong UK–Taiwan Ties

Next Story

Aditi Reinvents Saree Aesthetic

Latest from -Top News

Pakistan Risks Overstretching Itself in Yemen War

Pakistan’s expanding military role in Saudi Arabia amid the Yemen conflict could strain its defence resources and fragile finances…reports Asian Lite News Desk Pakistan’s military involvement in the war in Yemen may prove unsustainable because of mounting financial pressures and competing security demands, according to a new report. Islamabad’s growing military presence in Saudi Arabia risks stretching its defence resources while exposing the country to greater strategic and economic challenges. An article by Andrew Wilson in One World Outlook describes Pakistan’s involvement as a case of “fiscal and strategic overreach”, arguing that the country lacks the financial flexibility to sustain an expanded military commitment. Pakistan’s external finances depend heavily on an International Monetary Fund (IMF) programme, financial support from Gulf countries and remittances from Pakistani workers in the region. The report argues that deeper military involvement in the conflict could place additional pressure on these sources of financial stability. It also warns that deploying troops and military equipment abroad could weaken Pakistan’s capacity to address security challenges along its eastern border and deal with two domestic insurgencies. The move could also draw Islamabad into a conflict it has sought to approach cautiously. A Reuters report in May, citing Pakistani security and government sources, said Islamabad had deployed around 8,000 troops, a squadron of approximately 16 aircraft, mostly JF-17 fighter jets, two drone squadrons and a Chinese HQ-9 air-defence battery to Saudi Arabia. According to those sources, Riyadh was financing the deployment, with Pakistani personnel operating the equipment. The sources also said a confidential agreement contemplated the possibility of deploying up to 80,000 troops. Islamabad has not confirmed those figures, although it has acknowledged its military presence in Saudi Arabia, including the deployment of fighter jets at King Abdulaziz Air Base from April. The One World Outlook article argues that Saudi financial support can cover allowances and operating expenses but cannot easily replace military equipment needed elsewhere or resolve the political and strategic challenges of participating in the Yemen conflict. Pakistan’s defence budget is another concern. For the 2026-27 financial year, the federal government allocated PKR 3 trillion, or approximately $10.8 billion, to defence services. The allocation represents an 18 per cent increase from the original PKR 2.55 trillion provision and amounts to around 2.1 per cent of projected gross domestic product (GDP). Defence spending accounts for approximately 16 per cent of the federal government’s PKR 18.8 trillion expenditure. Military pensions are budgeted separately at PKR 822 billion, while debt servicing costs stand at approximately PKR 8 trillion, more than two-and-a-half times the defence allocation. The report argues that these competing financial obligations leave little room for additional military expenditure without placing further pressure on public finances. Pakistan’s reliance on IMF assistance also limits its fiscal flexibility. The country must meet the conditions attached to the programme, including a primary budget surplus target of 2 per cent of GDP and continued restraint on development spending. According to the article, these requirements make it difficult for Islamabad to finance an additional military commitment without compromising other budgetary priorities. Pakistan’s economic indicators offer limited reassurance. Economic growth for the 2025-26 financial year is estimated at between 3.6 and 3.7 per cent, while inflation reached approximately 10.3 per cent in September following an energy price shock. Foreign exchange reserves stood at around $21.5 billion at the end of September. Although this marks an improvement from the low levels recorded in 2023, the report notes that the reserves cover only a few months of imports. Financial assistance from Gulf partners remains central to Pakistan’s external stability. The article says Islamabad holds approximately $8 billion in Saudi deposits at its central bank. In July, the State Bank of Pakistan said Riyadh had extended the maturity of $5 billion in deposits to December 2028, easing the country’s immediate external financing requirements. A further $3 billion deposit was also extended in the spring. However, the article argues that these arrangements provide temporary relief rather than long-term financial independence, particularly as regional conflict threatens the stability of the Gulf economies on which Pakistan relies. The report concludes that Pakistan faces a difficult balance between supporting Saudi Arabia militarily and preserving the financial and military resources needed to address its domestic and regional challenges.
Go toTop