October 16, 2021
3 mins read

‘India To Be $4Tn Economy By FY25, Not $5 Tn’

In 2019, India ‘s Prime Minister Narendra Modi had set a $5 trillion target, reports Asian Lite News

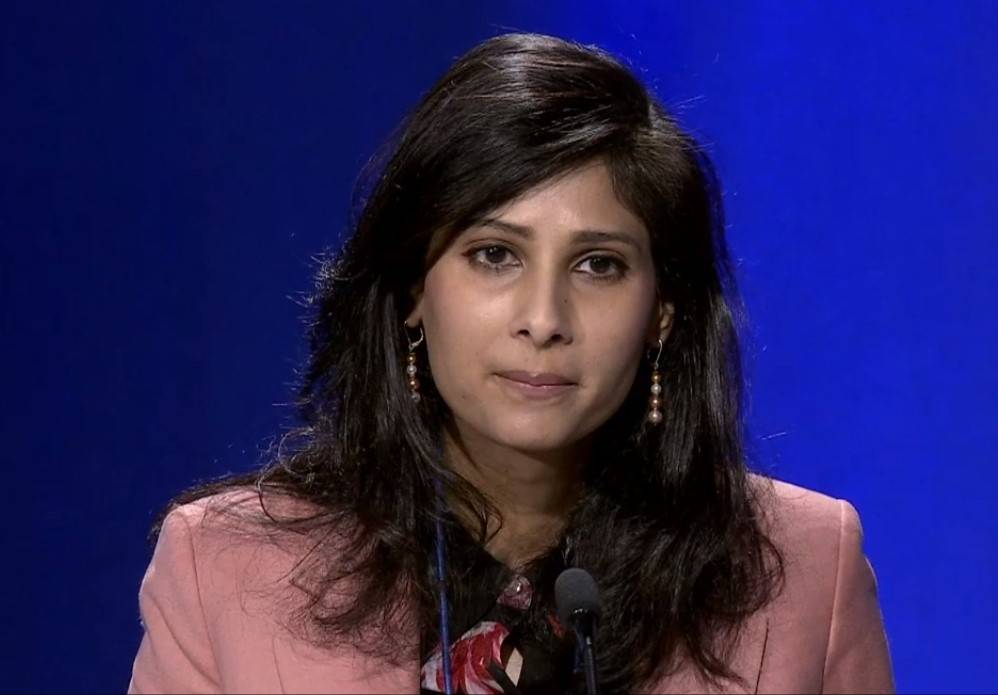
India is unlikely to become a $5 trillion economy by 2024-25, but will be worth about $4 trillion, Gita Gopinath, the International Monetary Fund’s (IMF) Chief Economist, has estimated, according to a Fortune India report.

Earlier, Prime Minister Narendra Modi had set the $5 trillion target in 2019.

“India has significant potential for rapid growth over the medium term given its young population, large labour force, and rising educational attainment”, though “there remain certain structural impediments that need to be addressed to harness this potential,” Gopinath told Fortune India.
She said there is a need for increased public expenditure in infrastructure, education, health and social safety nets.
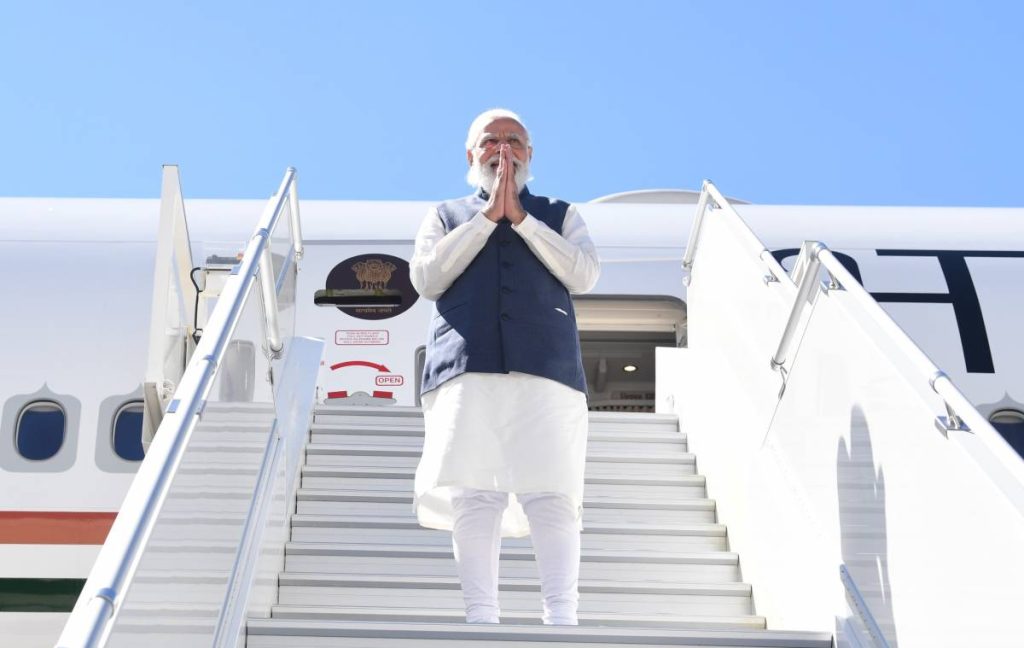
Prime Minister Narendra Modi

“But for this to happen greater fiscal space is needed. This can be enhanced through a credible and communicated medium-term fiscal consolidation strategy that includes additional revenue mobilization and advancement of the authorities’ privatisation agenda,” she said.

Last week, the IMF had released a flagship report that showed India continuing to be the world’s fastest growing major economy clocking a growth rate of 9.5 per cent this fiscal year and 8.5 per cent in the next.

The IMF’s World Economic Outlook (WEO) report kept the gross domestic product (GDP) growth projections it had made in July while India was in the grip of Covid-19’s second wave and had cut by 3 per cent its forecast of 12.5 per cent made in April before the pandemic’s resurgence.

Briefing reporters at the release of the report in Washington, Gopinath said: “India, came out of a very, very tough second wave and that led to a big downgrade in July but we have no change.”

“India is doing well in terms of vaccination rates and that’s certainly helpful,” she said. India does, however, face many challenges, she noted.

India
India’s FInance Minister Nirmala Sitharaman

“As of now, you know there are many challenges that the Indian economy always does face with regard to the financial market, with regard to the fact that the virus has not gone yet,” Gopinath said.

Asked if the large fiscal deficit in India was a major concern, Malhar Nabar, the Deputy Division Chief in IMF Research Department, said that while a medium-term strategy was needed to bring it down, it was still possible to meet the pressures from any future pandemic upsurge.

“We think that there’s still room to provide more support if needed, if the pandemic takes a turn for the worse, and to provide it in a targeted manner to the worst affected households and firms,” he said.

“But going forward over the medium term, it would be important to put in place, credible, medium term strategy to bring down the debt to GDP ratio and create space to meet the future development needs and infrastructure needs,” he added.
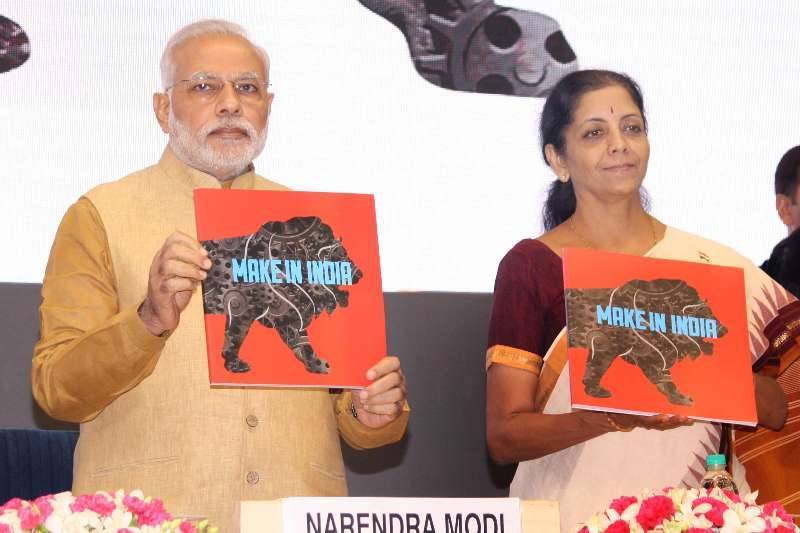
Prime Minister Narendra Modi and Finance Minister Nirmala Sitharaman

The WEO said that India’s Covid-battered economy had shrunk by 7.3 per cent in the last fiscal year.

Its long-term forecast for India’s GDP growth is 6.1 per cent in 2026.

In the WEO tables, China followed India with eight per cent this year and 5.6 per cent the next — a reduction of 0.1 per cent for both years from the forecast made in July.

The UK came next with 6.8 per cent growth this year, followed by France at 6.5 per cent, and the US at six per cent.

The global economy is projected to grow 5.9 per cent in 2021 and 4.9 per cent in 2022 — 0.1 percentage point lower for 2021 than in the July forecast.
Newsdesk

Newsdesk

Aravind Rajeev is Deputy News Editor at Asian Lite, mostly covering the Middle East and GCC. He has over eight years of experience as a journalist, with a background in ground-level reporting, crime reporting, as well as international and regional news.

Previous Story

KERALA RAINS: 8 Dead, 4 Missing, Army Deployed

Next Story

DASU BLAST: China Demands $38Mn From Pakistan

Previous Story

KERALA RAINS: 8 Dead, 4 Missing, Army Deployed

Next Story

DASU BLAST: China Demands $38Mn From Pakistan

Latest from -Top News

Pakistan Risks Overstretching Itself in Yemen War

Pakistan’s expanding military role in Saudi Arabia amid the Yemen conflict could strain its defence resources and fragile finances…reports Asian Lite News Desk Pakistan’s military involvement in the war in Yemen may prove unsustainable because of mounting financial pressures and competing security demands, according to a new report. Islamabad’s growing military presence in Saudi Arabia risks stretching its defence resources while exposing the country to greater strategic and economic challenges. An article by Andrew Wilson in One World Outlook describes Pakistan’s involvement as a case of “fiscal and strategic overreach”, arguing that the country lacks the financial flexibility to sustain an expanded military commitment. Pakistan’s external finances depend heavily on an International Monetary Fund (IMF) programme, financial support from Gulf countries and remittances from Pakistani workers in the region. The report argues that deeper military involvement in the conflict could place additional pressure on these sources of financial stability. It also warns that deploying troops and military equipment abroad could weaken Pakistan’s capacity to address security challenges along its eastern border and deal with two domestic insurgencies. The move could also draw Islamabad into a conflict it has sought to approach cautiously. A Reuters report in May, citing Pakistani security and government sources, said Islamabad had deployed around 8,000 troops, a squadron of approximately 16 aircraft, mostly JF-17 fighter jets, two drone squadrons and a Chinese HQ-9 air-defence battery to Saudi Arabia. According to those sources, Riyadh was financing the deployment, with Pakistani personnel operating the equipment. The sources also said a confidential agreement contemplated the possibility of deploying up to 80,000 troops. Islamabad has not confirmed those figures, although it has acknowledged its military presence in Saudi Arabia, including the deployment of fighter jets at King Abdulaziz Air Base from April. The One World Outlook article argues that Saudi financial support can cover allowances and operating expenses but cannot easily replace military equipment needed elsewhere or resolve the political and strategic challenges of participating in the Yemen conflict. Pakistan’s defence budget is another concern. For the 2026-27 financial year, the federal government allocated PKR 3 trillion, or approximately $10.8 billion, to defence services. The allocation represents an 18 per cent increase from the original PKR 2.55 trillion provision and amounts to around 2.1 per cent of projected gross domestic product (GDP). Defence spending accounts for approximately 16 per cent of the federal government’s PKR 18.8 trillion expenditure. Military pensions are budgeted separately at PKR 822 billion, while debt servicing costs stand at approximately PKR 8 trillion, more than two-and-a-half times the defence allocation. The report argues that these competing financial obligations leave little room for additional military expenditure without placing further pressure on public finances. Pakistan’s reliance on IMF assistance also limits its fiscal flexibility. The country must meet the conditions attached to the programme, including a primary budget surplus target of 2 per cent of GDP and continued restraint on development spending. According to the article, these requirements make it difficult for Islamabad to finance an additional military commitment without compromising other budgetary priorities. Pakistan’s economic indicators offer limited reassurance. Economic growth for the 2025-26 financial year is estimated at between 3.6 and 3.7 per cent, while inflation reached approximately 10.3 per cent in September following an energy price shock. Foreign exchange reserves stood at around $21.5 billion at the end of September. Although this marks an improvement from the low levels recorded in 2023, the report notes that the reserves cover only a few months of imports. Financial assistance from Gulf partners remains central to Pakistan’s external stability. The article says Islamabad holds approximately $8 billion in Saudi deposits at its central bank. In July, the State Bank of Pakistan said Riyadh had extended the maturity of $5 billion in deposits to December 2028, easing the country’s immediate external financing requirements. A further $3 billion deposit was also extended in the spring. However, the article argues that these arrangements provide temporary relief rather than long-term financial independence, particularly as regional conflict threatens the stability of the Gulf economies on which Pakistan relies. The report concludes that Pakistan faces a difficult balance between supporting Saudi Arabia militarily and preserving the financial and military resources needed to address its domestic and regional challenges.

UK and Germany Ratify Kensington Treaty

Britain and Germany ratify the Kensington Treaty, agreeing new cooperation on AI, quantum research, defence and security while targeting investment, jobs and Russian hybrid threats…reports Asian Lite News Desk Britain and Germany

Economic tide is turning in Bangladesh

If there is one thing that can bring some comfort to the struggling Bangladeshi economy, it is good relations with India. Bangladesh should remember that Delhi’s backing, through easy supplies of essentials
Go toTop

Don't Miss

Banking Giants Feel the Heat from RBI

RBI said this action is based on the deficiencies in

5 policemen injured, vehicles burnt in Kerala clash

Police arrived at the scene and tried to disperse the